Westlands
Oakman Insurance Agency
Affordable Medical Insurance in Kenya – Quality Healthcare Without Stretching Your Budget
Low-cost medical cover designed for self-employed individuals, young adults, and growing families.
Medical insurance should not be something you only consider when your income becomes high enough to afford an expensive corporate-style scheme. For many Kenyans, the more practical question is: how can I get meaningful medical protection while keeping my annual healthcare budget under control?
This budget-focused medical cover is built around a single annual medical limit. You select the level of protection that fits your budget, and eligible inpatient and outpatient treatment can draw from that overall annual limit, subject to the applicable outpatient cap, waiting periods, benefit conditions and policy terms.
That makes the structure particularly relevant to young professionals, self-employed people, young couples, families with children and anyone moving from employer-sponsored medical cover to an individually purchased plan.
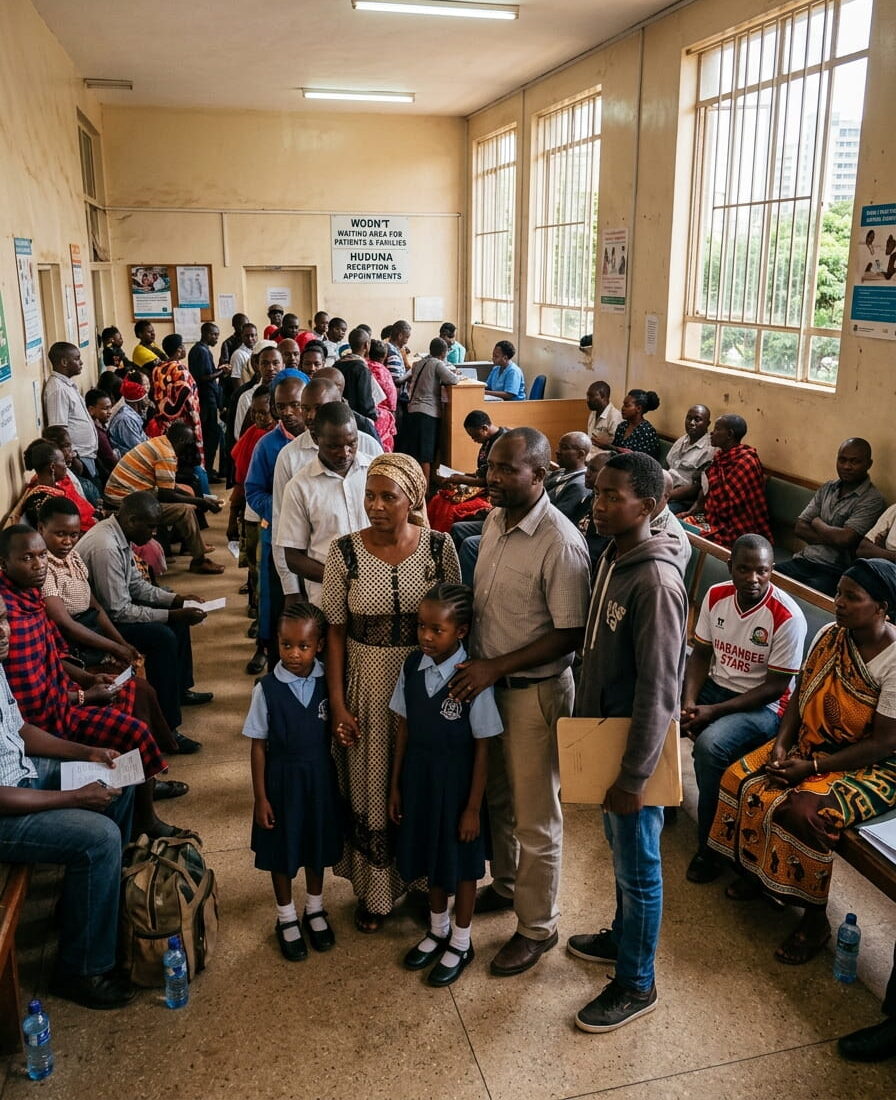
What Makes This a Budget Medical Insurance Plan?
Smart Value StructureThe objective is not simply to offer cheap medical insurance in Kenya with compromised terms. It is to give you a defined amount of annual medical protection that you can realistically maintain while still covering the types of healthcare expenses that can put pressure on a household budget.
Instead of separating your money into completely different pots for hospitalisation and routine care, the plan uses a single limit medical insurance structure. This means the cover can respond flexibly to your healthcare needs during the year, with the 30% outpatient medical cover cap ensuring robust protection for both inpatient and day-to-day medical visits.
Single Annual Medical Limit
Draw both inpatient and outpatient care from one flexible overall limit, maximizing benefit utilization throughout the year.
30% Outpatient Allocation
Up to 30% of your single limit is dedicated to outpatient treatment, GP consultations, and lab tests without requiring separate premiums.
No Outpatient Co-Payment
Enjoy cashless visits with no extra co-payment or visit fee at empanelled clinics under standard product conditions.
Flexible Installment Options
Ease financial commitment with convenient installment arrangements available for retail healthcare policies.
Prescriptions & Emergency Evacuation
Includes covered prescription drugs, road ambulance services, and emergency air evacuation on eligible limits.
Widespread Provider Network
Access hassle-free medical services across leading empanelled hospitals and clinics throughout Nairobi and Kenya.
Want to see how a single limit medical cover fits your budget?
Single Annual Medical Limit: The Core Concept
Key Policy StructureUnderstanding how a single limit medical insurance structure operates is essential when selecting affordable medical insurance in Kenya. The plan is built around one overall annual medical limit, giving you complete flexibility to draw treatment from a single pool without paying for unneeded separate benefit caps.
Select an annual limit that aligns with your family size, health profile, and budget. The standard cover options include:
KES 100,000
KES 250,000
KES 500,000
KES 750,000
KES 1,000,000
KES 1,500,000
KES 2,000,000
It is important to note that the outpatient allocation is not added on top of your chosen annual limit. Instead, outpatient services can utilize up to 30% of the overall annual limit. In other words, your outpatient entitlement is a shared portion of the same overall medical pool, ensuring that up to 30% of the inpatient cover can be flexibly deployed for routine doctor visits, prescriptions, and lab tests.
How the 30% Outpatient Medical Cover Allocation Works in Practice:
Example Scenario: On a KES 500,000 annual limit plan, your 30% maximum outpatient allocation is KES 150,000.
If you incur KES 50,000 in eligible routine outpatient treatment during the year, your remaining overall medical pool for hospitalisation or further treatment stands at KES 450,000 (subject to policy terms and any previous claims).
This flexible structure makes it one of the most practical options for family medical cover in Kenya, self-employed individuals, and young professionals seeking budget medical cover for families without sacrificing inpatient protection.
Unsure which single limit option is best for your household?
Your Medical Limit – 30% Outpatient and 70% Inpatient
Benefit Split ScheduleUnderstanding your coverage under our single limit medical insurance Kenya plans is very simple: the overall amount you choose is your total medical cover for the policy year. Up to 30% can be used for outpatient treatment, while the remaining 70% is available for inpatient hospitalisation and other eligible medical expenses, subject to policy terms.
| Annual Medical Limit | 30% Outpatient Allocation | 70% Inpatient Allocation |
|---|---|---|
| KES 100,000 | KES 30,000 | KES 70,000 |
| KES 250,000 | KES 75,000 | KES 175,000 |
| KES 500,000 | KES 150,000 | KES 350,000 |
| KES 750,000 | KES 225,000 | KES 525,000 |
| KES 1,000,000 | KES 300,000 | KES 700,000 |
| KES 1,500,000 | KES 450,000 | KES 1,050,000 |
| KES 2,000,000 | KES 600,000 | KES 1,400,000 |
A Simple Example – How Your Medical Cover Works in Practice
For example, if you choose a KES 250,000 medical cover for the year, up to KES 75,000 can be used for routine outpatient treatment (GP visits, lab tests, prescriptions) and KES 175,000 represents the remaining 70% for inpatient admission protection. Think of it as one KES 250,000 annual medical budget split into 30% for outpatient care and 70% for inpatient care.
If you use KES 20,000 for outpatient care, that amount is taken from your KES 75,000 outpatient portion. The plan is specifically engineered to give self-employed individuals, young adults, and families in Kenya both everyday healthcare support and protection against unexpected hospital bills.
Golden Rule: 30% for outpatient care and 70% for inpatient care.
Need help selecting between KES 100K to KES 2M annual limits?
What Is Covered? Comprehensive Inpatient & Outpatient Scope
Core Benefits ScopeOur affordable medical insurance in Kenya combines core hospitalisation protection with flexible routine healthcare under a single annual medical limit. Explore the detailed breakdown of what is covered under both inpatient and outpatient care:
Inpatient Medical Cover
Inpatient cover is designed to protect you when illness or injury requires hospital admission. This is where budget medical cover in Kenya provides vital financial security, preventing unexpected hospital bills from straining family savings.
- Eligible hospitalisation and ward accommodation
- Hospital accommodation and professional nursing care
- Doctors', surgeons', and anesthetists' fees
- Surgical procedures and theatre charges
- Eligible diagnostic investigations (X-rays, MRI, CT scans)
- Prescription medicines and medical consumables
- Specialist treatment through our empanelled hospital network
- Eligible day-care surgery and minor procedures
- Eligible emergency treatment and stabilization
- Eligible post-hospitalisation physiotherapy and rehabilitation
Outpatient Cover (Up to 30% of Limit)
Outpatient cover provides for routine healthcare costs where hospital admission is not required. Designed for self-employed individuals and families in Nairobi and across Kenya to manage day-to-day medical visits efficiently.
- General practitioner (GP) consultations
- Specialist medical consultations within the provider panel
- Laboratory tests and diagnostic investigations
- Diagnostic imaging, routine pathology, and X-rays
- Prescription medicines dispensed by accredited pharmacies
- Eligible follow-up outpatient treatment and dressing
- Eligible minor outpatient surgical procedures
- Other medically indicated outpatient healthcare services
Have questions about specific inpatient or outpatient coverage limits?
Cashless Access, Emergencies & Prescription Benefits
Provider Panel & Key PerksWhen selecting affordable medical insurance in Kenya, understanding how services are accessed is essential. Our budget medical cover eliminates out-of-pocket stress by utilizing a direct cashless network across our accredited hospital network in Kenya.
No Reimbursement – Direct Provider Access
This plan does not operate on a reimbursement model. Covered inpatient and outpatient treatments (including specialist care) are accessed directly within our approved medical insurance hospital network in Kenya. You do not need to pay out-of-pocket and wait weeks to claim back your funds.
Emergency Ambulance & Evacuation
Medical emergencies present two hurdles: treatment costs and emergency transport. Core benefits include emergency road ambulance services and air evacuation to transfer patients swiftly to the nearest accredited medical facility without unexpected out-of-pocket bills.
Full Prescription Drug Coverage
Prescription drugs can become a recurring monthly expense for young families and self-employed individuals. Eligible prescription medicines prescribed during covered outpatient visits or inpatient stays draw directly from your single annual medical limit.
Important Step Before Treatment: Always confirm that your preferred hospital, clinic, or specialist is active on our medical insurance hospital panel in Kenya prior to your visit, and verify if pre-authorisation is required for non-emergency procedures.
Want to verify if your local clinic or hospital is on our approved network panel?
Maternity and Pregnancy-Related Cover
10-Month Waiting PeriodFor young couples and growing families seeking affordable maternity medical insurance in Kenya, pregnancy protection is often a central consideration. Under our budget plan conditions, pregnancy, childbirth, and non-accident-related surgical procedures carry a 10-month waiting period for both inpatient admissions and outpatient antenatal/postnatal consultations.
This timeline means that individuals or couples planning to expand their family should arrange their cover well in advance. Purchasing a medical policy after pregnancy has already begun will not bypass or reduce the mandatory 10-month maternity waiting period.
Once active, eligible maternity care—including normal deliveries, Caesarean sections, and pregnancy complications—draws directly from your single annual medical limit subject to applicable policy conditions. Always verify current maternity limits when requesting your quotation through Oakman Insurance Agency.
Planning Ahead is Key: Because of the standard 10-month waiting period, it is crucial to activate your policy prior to conception to guarantee seamless coverage for antenatal care, delivery, and postnatal care within our accredited hospital network.
Planning a family? Ask us about maternity limits and waiting period terms today.
Dental and Optical Bonus Benefits
Added Value BenefitsOne of the standalone features that adds tremendous value to this affordable medical insurance in Kenya plan is the inclusion of bonus dental and optical benefits. Unlike plans that force you to buy expensive standalone riders, these extra benefit limits are automatically tied to your selected annual medical cover option.
| Annual Medical Limit | Dental Bonus Limit | Optical Bonus Limit |
|---|---|---|
| KES 100,000 | KES 5,000 | KES 5,000 |
| KES 250,000 | KES 5,000 | KES 5,000 |
| KES 500,000 | KES 5,000 | KES 5,000 |
| KES 750,000 | KES 7,500 | KES 7,500 |
| KES 1,000,000 | KES 10,000 | KES 10,000 |
| KES 1,500,000 | KES 10,000 | KES 10,000 |
| KES 2,000,000 | KES 15,000 | KES 15,000 |
Smart Healthcare Protection for the Whole Family
Whether you need routine dental checks, teeth cleaning, fillings, or prescription optical frames and lenses, having medical insurance with dental cover in Kenya and medical insurance with optical cover in Kenya ensures everyday health needs are handled seamlessly without extra financial strain on your household budget.
Have questions about dental or optical provider empanelment?
Real Value: What Dental and Optical Cover Means For You
Practical Family ProtectionHaving medical insurance with dental cover in Kenya and medical insurance with optical cover in Kenya integrated into your budget plan turns unpredictable out-of-pocket expenses into reliable, structured care. Here is how these bonus limits protect your everyday healthcare budget:
What Dental Cover Means For Your Family
Dental care is frequently postponed because families view it as an unexpected, separate out-of-pocket expense. A dedicated bonus dental benefit gives you a defined financial cushion to cover essential oral healthcare needs before minor issues escalate.
- Routine dental consultations where covered by policy terms
- Eligible non-cosmetic dental treatments (cleanings, fillings, extractions)
- Medically indicated dental procedures within your allocated bonus limit
What Optical Cover Means For You
For self-employed professionals, students, and family members relying on corrective vision care, optical costs can quickly add up. An integrated optical benefit ensures your vision needs are met without stretching your monthly budget.
- Comprehensive eye examinations and vision consultations
- Eligible prescription vision-correction lenses and corrective eyewear
- Essential optical care covered up to your plan's specific bonus entitlement
Important Step Before Consultation: As with all non-emergency services, always utilize our empanelled medical network and verify approved dental clinics or optical centers with Oakman Insurance Agency before receiving treatment.
Need assistance finding an empanelled dental or optical provider near you?
Wellness Programme: Healthcare Beyond Treatment
Our commitment extends beyond paying claims to supporting preventive healthcare. The exact wellness services available depend on current partner arrangements—ask Oakman Insurance for the latest wellness schedule when requesting your quote.
Who Can Join This Medical Insurance Scheme?
Broad EligibilityFinding affordable medical insurance in Kenya shouldn't be restricted by age or employment type. This scheme features exceptionally broad enrolment criteria—welcoming self-employed individuals, young adults, seniors, and families across Kenya.
| Who Can Join | Eligibility Criteria & Conditions |
|---|---|
| Principal Member | Birth to 100 years, subject to underwriting evaluation and terms |
| Spouse | Eligible legal spouse of the principal member |
| Own Children | Birth to 18 years |
| Legally Adopted Children | Birth to 18 years |
| Foster Children | Birth to 18 years |
| Dependant Children (18–24 years) | Can remain covered under family policy with valid proof of schooling |
Medical Examination & Accurate Disclosure
Not every applicant automatically receives cover simply by paying a premium. The insurer assesses medical disclosure in the application form prior to acceptance. Applicants should disclose all material health history accurately, as non-disclosure can affect claim admissibility.
Waiting Periods: What You Need to Know Before Buying
Timelines ScheduleWaiting periods apply before specific claims become admissible. Even low cost medical cover in Kenya cannot be purchased retroactively after an illness or condition starts, making it essential to secure protection before medical issues arise.
| Medical Situation / Condition | Qualifying Waiting Period |
|---|---|
| Pre-existing / Chronic Conditions (Inpatient) | 10 months |
| Pre-existing / Chronic Conditions (Outpatient) | 3 months |
| Non-Accident Surgeries (Inpatient & Outpatient) | 10 months |
| Pregnancy & Childbirth (Inpatient & Outpatient) | 10 months |
| General Illness Admissions & Outpatient Visits | 1 week (7 days) |
| Groups above 15 People | No waiting period under published conditions |
Special Advantage for Groups & Employers (15+ Members)
Groups with more than 15 members enjoy a waiver on standard waiting periods under published product conditions! This is highly beneficial for corporate SMEs, chama groups, professional associations, and organized groups seeking immediate group medical cover.
Ready to verify eligibility or get a group waiting period waiver quote?
Provider Network Across Kenya – Access to Quality Healthcare
FLEXI Hospital PanelA budget medical cover in Kenya is only truly effective if you can access convenient healthcare providers near your home or workplace. Our scheme connects members to an extensive FLEXI medical insurance hospital network in Kenya spanning major medical centers, clinics, specialized eye centers, and diagnostic facilities nationwide.
Equity Afia Medical Centre
Ruai Family Hospital (RFH)
Penda Medical Centre
Bliss GVS Healthcare
Medicross Medical Centre
Bristol Park Hospital
Radiant Group of Hospitals
Family Care Medical Center (FHOK)
AIC Kijabe Hospital
Access Afya Kenya Limited
Reale Hospital
Oasis Healthcare
Optica Ltd
Lions SightFirst Eye Hospital
Your Pre-Treatment Network Checklist:
- Verify Active Panel Status: Check whether your preferred hospital or clinic is currently active on the panel list before visiting.
- Specialist Access: Confirm if your specialist can be accessed cashless through our empanelled network.
- Pre-Authorisation Requirements: Confirm whether planned procedures require prior approval from the insurer.
- Specific Treatment Capability: Ask whether the specific facility offers the exact service or treatment you need under your plan.
Strict Policy Rule – No External Reimbursements: Do not assume that paying a provider outside the approved panel out of pocket will create a reimbursement claim. Because this policy operates strictly on a cashless network basis, non-empanelled provider visits will not be reimbursed. Always confirm provider status with Oakman Insurance Agency before receiving non-emergency care.
Want to confirm if a hospital or clinic near you is on our panel?
Affordable Medical Insurance Premium Rates in Kenya
Transparent Annual PricingFinding affordable medical insurance in Kenya begins with transparent pricing. Below is the published annual rate structure for members aged 0–64 and senior members aged 65+. Rates vary by family size, starting from the principal member alone (M) up to principal plus 4 dependants (M + 4).
Annual Premium Rates – Members Aged 0–64
Standard Family Cover| Family Size | 100K Limit | 250K Limit | 500K Limit | 750K Limit | 1M Limit | 1.5M Limit | 2M Limit |
|---|---|---|---|---|---|---|---|
| M (Single) | KES 14,574 | KES 19,824 | KES 29,738 | KES 41,632 | KES 60,367 | KES 94,535 | KES 129,324 |
| M + 1 | KES 21,132 | KES 36,720 | KES 55,080 | KES 77,113 | KES 111,813 | KES 175,100 | KES 239,536 |
| M + 2 | KES 28,528 | KES 51,499 | KES 77,248 | KES 108,148 | KES 156,815 | KES 245,571 | KES 335,942 |
| M + 3 | KES 34,234 | KES 63,111 | KES 94,665 | KES 132,532 | KES 192,172 | KES 300,941 | KES 411,686 |
| M + 4 | KES 40,054 | KES 72,577 | KES 108,866 | KES 152,412 | KES 220,997 | KES 346,082 | KES 473,440 |
Annual Premium Rates – Senior Members Aged 65+
Seniors Healthcare Cover| Family Size | 100K Limit | 250K Limit | 500K Limit | 750K Limit | 1M Limit | 1.5M Limit | 2M Limit |
|---|---|---|---|---|---|---|---|
| M (Single Senior) | KES 20,377 | KES 30,455 | KES 44,332 | KES 60,985 | KES 90,232 | KES 139,775 | KES 192,805 |
| M + 1 | KES 37,698 | KES 54,108 | KES 79,813 | KES 110,658 | KES 164,830 | KES 256,595 | KES 354,819 |
| M + 2 | KES 54,756 | KES 74,799 | KES 110,848 | KES 154,107 | KES 230,081 | KES 358,779 | KES 496,534 |
| M + 3 | KES 67,103 | KES 91,055 | KES 135,232 | KES 188,245 | KES 281,349 | KES 439,064 | KES 607,879 |
| M + 4 | KES 77,168 | KES 104,307 | KES 155,112 | KES 216,077 | KES 323,146 | KES 504,519 | KES 698,656 |
Important Quotation Note: Published rates serve as an educational guide. Premium rates are subject to underwriting approval and statutory levies. Always confirm current exact rates with Oakman Insurance Agency before policy placement.
Example: Single Individual (Age 0–64)
For a self-employed professional or young adult purchasing individual medical cover, premiums start at KES 14,574 annually for a KES 100,000 single limit.
| Annual Limit | Annual Premium | 30% Outpatient |
|---|---|---|
| KES 100,000 | KES 14,574 | KES 30,000 |
| KES 250,000 | KES 19,824 | KES 75,000 |
| KES 500,000 | KES 29,738 | KES 150,000 |
| KES 750,000 | KES 41,632 | KES 225,000 |
| KES 1,000,000 | KES 60,367 | KES 300,000 |
| KES 1,500,000 | KES 94,535 | KES 450,000 |
| KES 2,000,000 | KES 129,324 | KES 600,000 |
Example: Family of Three (M + 2, Age 0–64)
For a young couple with one child or a single parent with two children (M + 2 structure), premiums range from KES 28,528 to KES 335,942 depending on the selected limit.
| Annual Limit | Published Premium | 30% Outpatient |
|---|---|---|
| KES 100,000 | KES 28,528 | KES 30,000 |
| KES 250,000 | KES 51,499 | KES 75,000 |
| KES 500,000 | KES 77,248 | KES 150,000 |
| KES 750,000 | KES 108,148 | KES 225,000 |
| KES 1,000,000 | KES 156,815 | KES 300,000 |
| KES 1,500,000 | KES 245,571 | KES 450,000 |
| KES 2,000,000 | KES 335,942 | KES 600,000 |
Ready to get an exact custom quote for your exact family size?
What Makes This Cover Different From Paying Cash for Healthcare?
Financial Risk ComparisonPaying out of pocket for healthcare might seem like an easy option when everyone in your home is healthy. However, healthcare needs are inherently unpredictable. A sudden illness, unexpected surgery, or emergency hospital admission can quickly deplete savings and overwhelm a household budget.
Paying Cash Out-of-Pocket
- Unpredictable Expenses: Medical costs hit without warning, creating sudden financial pressure.
- Drains Family Savings: High hospital bills can wipe out emergency funds, investments, or business capital.
- Delayed Treatment Risk: Families often postpone necessary medical checkups to save cash upfront.
Budget Medical Cover Structure
- Predictable Annual Premium: You pay a fixed, affordable annual premium that fits cleanly into your budget.
- Transfers Financial Risk: Transfers heavy hospitalisation costs (up to KES 2M) directly to the insurer.
- Peace of Mind Protection: Cashless access across our medical insurance hospital network in Kenya.
More Than Just Routine Doctor Visits:
The true value of affordable medical insurance in Kenya isn't measured solely by the number of routine clinic visits you make in a year. Its greatest strength is the guaranteed financial cushion available when an unexpected illness or admission occurs—protecting your hard-earned savings from devastating medical debt.
Protect your hard-earned savings today with a budget-friendly plan.
Is a Lower Annual Limit Enough for Your Household?
Smart Plan Selection GuideDeciding on the right level of coverage depends entirely on your family size, health profile, and overall financial setup. An entry-level limit such as KES 100,000 or KES 250,000 serves as a practical, low-cost starting point for young adults or self-employed individuals seeking basic protection against unexpected healthcare bills while keeping annual premiums minimal.
However, if you have dependants, frequent outpatient healthcare needs, or concerns regarding major hospital admissions, selecting a higher annual medical limit (such as KES 500,000 to KES 2,000,000) provides a far sturdier financial safety net for your family.
The Essential Question When Buying Medical Cover:
The right evaluation is not simply "Which plan is cheapest?" It is "What medical bill could seriously disrupt my household finances, and how much annual protection can I realistically maintain?"
Complete Summary: Benefits That Add Value to Your Plan
Package HighlightsChoosing an affordable medical insurance cover in Kenya through Oakman Insurance Agency delivers an all-inclusive healthcare package designed for complete peace of mind:
Single annual limit for flexible inpatient & outpatient protection
30% outpatient allocation cap drawn from single overall pool
Emergency road ambulance transport included
Emergency air evacuation for critical life-saving care
Full prescription drug coverage for covered conditions
Bonus dental benefit tied to chosen limit
Bonus optical benefit for eyewear & eye examinations
Extensive preventive wellness programme schedule
Broad FLEXI hospital network across Nairobi & Kenya
Flexible premium installment payment arrangements
Waiver of waiting period for groups above 15 members
Broad Lifelong Access: Scheme eligibility extends from birth up to age 100, ensuring children, adults, seniors, and multi-generational families in Kenya can access affordable medical protection subject to standard underwriting terms.
Need help selecting the right limit or setting up flexible payments?
Key Policy Guidelines: Things You Should Know Before Choosing Your Cover
Essential Terms & ConditionsBefore purchasing your affordable medical insurance cover in Kenya, reviewing key operational terms ensures complete transparency and a smooth experience when accessing healthcare at empanelled facilities.
30% Outpatient Allocation Cap
Outpatient medical expenses are capped at 30% of your chosen overall annual medical limit.
Outpatient Bills Above KES 6,000
Outpatient treatment bills exceeding KES 6,000 require pre-authorisation prior to service delivery.
No Out-of-Panel Reimbursements
Covered services are strictly accessed direct/cashless through our accredited medical insurance hospital network in Kenya; no reimbursement is made for outside payments.
Specialist Consultation Panel
Specialist medical consultations must be accessed through empanelled specialist providers within the approved network.
Medical Underwriting Evaluation
All membership applications are subject to medical underwriting review prior to formal policy issuance.
Seniors Medical Examination
Medical exams may be required for applicants aged 55 years and above or where underwriters request additional records.
Pre-Existing Chronic Inpatient (10 Months)
Inpatient treatment for pre-existing or chronic medical conditions carries a 10-month waiting period.
Pre-Existing Chronic Outpatient (3 Months)
Outpatient management for pre-existing or chronic conditions is subject to a 3-month waiting period.
Surgery & Maternity (10 Months)
Non-accident surgical procedures, pregnancy, and childbirth benefits carry a 10-month waiting period.
General Illness Visits (1 Week)
Outpatient consultations and inpatient admissions for standard acute illnesses carry a brief 1-week (7 days) waiting period.
Groups 15+ Waiting Period Waiver
Organized groups and corporate teams exceeding 15 members enjoy no waiting periods under published product conditions.
Important Approval Tip for Seamless Hospital Care:
When undergoing outpatient procedures or receiving lab work exceeding KES 6,000, ensure the medical provider submits a pre-authorisation request to the insurer before services are rendered. This guarantees instant cashless clearance without administrative delays.
Have questions about policy conditions or pre-authorisation terms?
What Is Not Covered? Policy Exclusions
General ExclusionsUnderstanding policy exclusions is just as critical as knowing your benefits when choosing affordable medical insurance cover in Kenya. Clear transparency upfront ensures you make informed healthcare decisions for your household without unexpected surprises at treatment time.
In accordance with standard insurance guidelines, the following procedures and treatments are excluded from coverage across all single limit options:
- Cosmetic Procedures: Cosmetic surgeries, aesthetic treatments, breast reduction, or breast augmentation surgeries.
- Infertility Treatments: Infertility evaluations, IVF, assisted reproductive technology, and related treatments.
- Hearing Aids: External hearing devices and non-medically indicated audiology appliances.
- Experimental Treatments: Investigative, unproven, or experimental medical treatments that fall outside accepted medical standards.
- Non-Indicated Expenses: Medical costs not medically indicated or non-compliant with recognized professional medical-board practice guidelines.
Transparent Guidance: For a complete list of standard policy exclusions or specific treatment inquiries, contact Oakman Insurance Agency before booking non-routine procedures.
Have a question about a specific medical procedure or treatment eligibility?
Frequently Asked Questions About Affordable Medical Insurance in Kenya
Instant AnswersFind quick answers to common questions regarding affordable medical insurance cover in Kenya, single annual limit splits, waiting periods, provider network usage, and premium options.
What is affordable medical insurance in Kenya?
Affordable medical insurance is a plan structured to provide meaningful healthcare protection at a premium that is manageable for the customer. This option uses a single annual medical limit with inpatient, outpatient, and other eligible benefits subject to applicable policy limits and conditions.
What is the cheapest medical insurance available?
There is no single cheapest option for everyone. Premium depends on the selected annual medical limit, family size, age, and medical underwriting. The published rate for a principal member aged 0–64 starts at KES 14,574 for a KES 100,000 annual limit.
Can I get medical insurance for under KES 20,000 per year?
Yes. Published rates show KES 14,574 for a principal member aged 0–64 on a KES 100,000 annual limit and KES 19,824 on a KES 250,000 limit. Current exact rates should be confirmed with Oakman Insurance Agency before purchase.
Does this medical insurance include outpatient cover?
Yes. Outpatient treatment is fully included as part of the plan, but it is capped at up to 30% of the overall annual medical limit.
How much outpatient cover do I get from a KES 500,000 medical limit?
The 30% outpatient cap equals KES 150,000. This is part of the same KES 500,000 annual medical pool, not an additional KES 150,000 on top of the limit.
Is there a co-pay or pre-authorisation required for outpatient visits?
Outpatient visits within our empanelled provider network are handled cashless. However, outpatient treatment bills exceeding KES 6,000 require prior pre-authorisation before services are rendered.
Can I pay first and claim reimbursement later?
No. Supplied policy conditions state that there is no reimbursement model. All covered services, including specialist consultations, must be accessed cashless directly within our approved provider network.
Does the cover include maternity?
Pregnancy and childbirth are covered subject to policy terms, but supplied conditions specify a mandatory 10-month waiting period for inpatient and outpatient maternity services.
Are pre-existing conditions covered?
Pre-existing and chronic conditions are subject to waiting periods and underwriting disclosure. Supplied conditions specify 10 months for inpatient expenses and 3 months for outpatient treatment relating to pre-existing or chronic conditions.
At what age can I buy this medical cover?
Published eligibility extends from birth up to 100 years, subject to medical underwriting evaluation and applicable policy conditions.
Can I cover my children?
Yes. Biological, legally adopted, and foster children can be covered from birth up to 18 years. Dependant children above 18 and below 25 can remain covered under the family policy when proof of active schooling is provided.
Do people over 55 need a medical examination?
Medical examinations may be required for applicants aged 55 years and above, or where the medical underwriting team specifically requests health records based on declared history.
Does the plan include dental and optical benefits?
Yes. Bonus dental and optical limits are automatically linked to your overall annual medical limit, ranging from KES 5,000 on lower plans up to KES 15,000 on the KES 2 Million plan.
Does the plan cover emergency ambulance services?
Yes. Emergency road ambulance services and emergency air evacuation are included among the core policy benefits.
Which hospitals can I use?
You must use our empanelled provider network. Our panel includes Equity Afia, RFH, Penda, Bliss GVS, Medicross, Bristol Park, Radiant, Family Care (FHOK), AIC Kijabe, Access Afya, Reale Hospital, Oasis Healthcare, Optica, and Lions SightFirst Eye Hospital, subject to the active panel list.
Is there a waiting period for general illness?
Published conditions state a one-week (7 days) waiting period for general illness admissions and outpatient visits. Longer waiting periods apply to maternity, non-accident surgeries, and pre-existing/chronic conditions.
Do groups get special waiting-period treatment?
Yes! Under published product terms, organized groups, corporate teams, chama groups, and associations with more than 15 members enjoy a waiver on standard waiting periods.
What are the main exclusions?
Main exclusions include cosmetic procedures, breast reduction/augmentation, infertility treatment, hearing aids, experimental/unproven treatments, and medical expenses not medically indicated under standard medical-board guidelines.
Is a budget medical plan suitable for a family?
It can be very suitable, particularly for families in Kenya looking for an affordable annual limit while understanding that the overall limit is shared. Families should compare the annual limit, 30% outpatient cap, waiting periods, and provider network before selecting a plan.
Have a question not listed here? Talk directly to our medical advisor.
How to Choose Your Annual Medical Limit: A Simple Guide
Selection FrameworkSelecting the right cover begins with evaluating your household's realistic healthcare requirements rather than focusing solely on the lowest initial premium. Use this quick decision checklist to determine the ideal limit for your family:
Household Decision Checklist:
- Family Size: How many principal members and dependants will be enrolled under the plan?
- Dependant Age Profile: Do you have young children who may require frequent outpatient pediatric consultations?
- Family Planning: Are you planning a pregnancy over the next 12 months (keeping in mind the 10-month maternity waiting period)?
- Financial Buffer: Would an unexpected KES 250,000 hospital admission bill severely disrupt your savings or business cash flow?
- Health History: Does anyone in your family have an existing chronic condition that requires continuous outpatient drug management?
- Hospital Preferences: Which specific medical facilities and clinics in Nairobi or across Kenya do you prefer visiting?
- Premium Sustainability: Can you comfortably maintain the chosen annual premium setup without risk of policy lapse?
Always compare your target annual medical limit against the corresponding 30% outpatient allocation. Because the outpatient cap is drawn directly from the main medical limit, selecting a higher overall option gives your family much needed room when major medical treatments arise during the policy year.
Get Affordable Medical Insurance in Kenya Today
Tailored SolutionsYou don't need to wait until you can afford a costly corporate scheme to protect your family's health. Oakman Insurance Agency offers customized guidance to compare flexible, budget-friendly medical plans tailored to your exact needs:
Individual Medical Cover
Medical Cover for Young Couples
Standalone Medical Cover for Children
Medical Cover for Self-Employed
Budget Maternity Medical Cover
Combined Inpatient & Outpatient Medical Insurance
Request Your Personalised Instant Medical Quote
Ready to secure affordable medical protection? Simply share your details with our team, and we will guide you through the exact premium breakdown, outpatient limits, waiting periods, and provider panels before you make your decision.
✓ Ages of Everyone to Cover
•
✓ Preferred Annual Limit (KES 100K - 2M)
•
✓ Preferred Town or Hospital
Trusted insurance partner for families and businesses across Kenya. We provide personalized coverage with integrity and care

Contact us
-
-
One Africa Place, 5th Floor, Waiyaki Way, Westlands, Nairobi, Kenya
-
+254 710 918 201
All rights Reserved by Oakman Insurance Agency